Modeling High-Frequency Limit Order Book Dynamics Using Machine Learning
-
Framework to capture the dynamics of high-frequency limit order books.

Overview
In this project I used machine learning methods to capture the high-frequency limit order book dynamics and simple trading strategy to get the P&L outcomes.
-
Feature Extractor
-
Rise Ratio
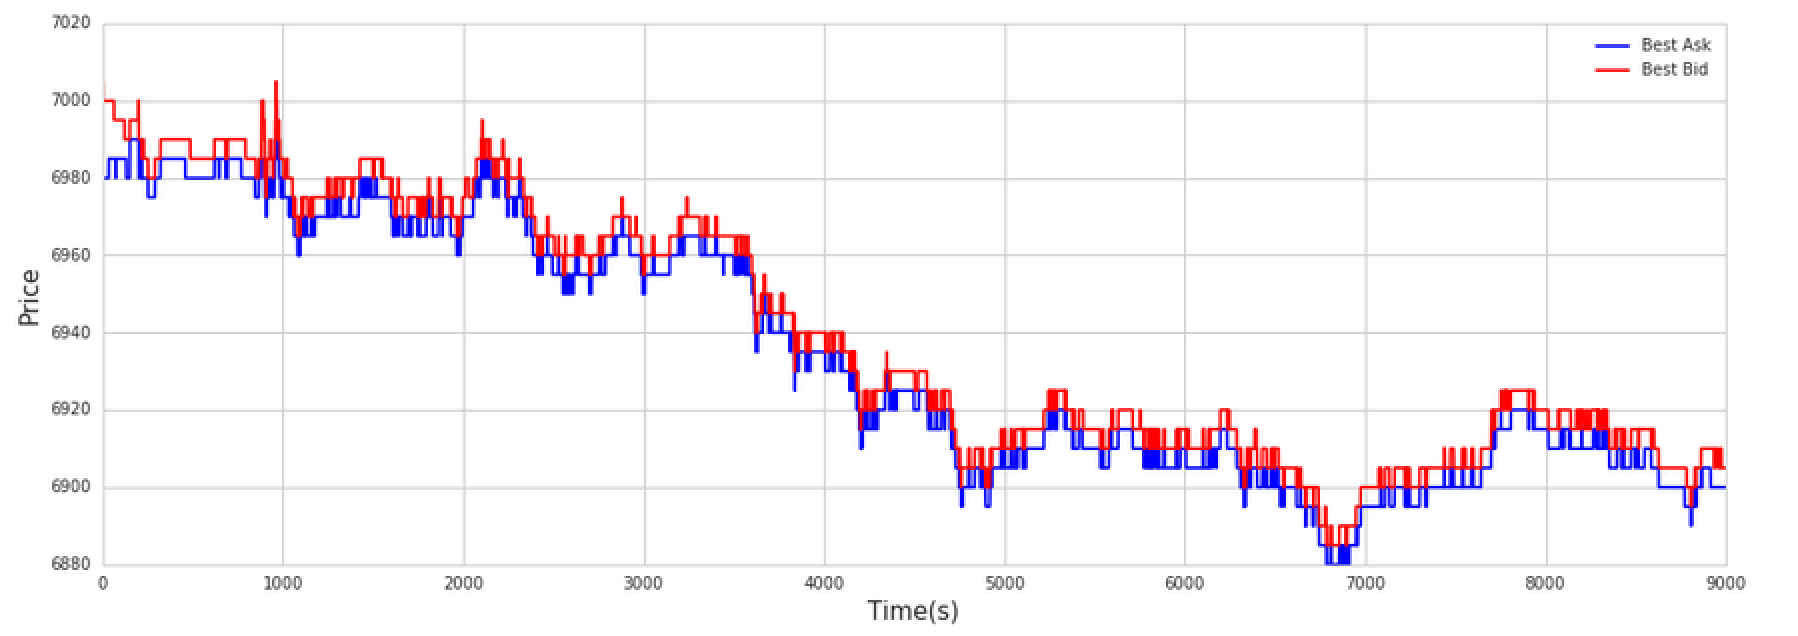
-
Depth Ratio

[Note] : [Feature_Selection] (Feature_Selection)
-
-
Learning Model Trainer
- RandomForestClassifier
- ExtraTreesClassifier
- AdaBoostClassifier
- GradientBoostingClassifier
- SVM
-
Use best model to predict next 10 seconds

-
Prediction outcome

-
Profit & Loss

[Note] : [Model_Selection] (Model_Selection)